

This piece is an update to two of the foundational deep dives of Crack The Market:
ASML ($ASML) was my first ever publication, in March 2025, written near the trough of the export control panic with a thesis that the company would 2.5x its EPS by 2030. The stock has returned more than 130% since, and the thesis has been pulled forward by roughly three years.
TSMC ($TSM) followed in January with the full case for the company manufacturing the world’s AI compute, up 30% since, and six months of delivery have strengthened every pillar of it.


These are, quite simply, two of the best businesses in the world, the two widest moats in the entire AI supply chain, and both just reported quarters that confirmed everything the original theses claimed while their share prices went the other way.
This shorter piece refreshes both cases around the Q2 2026 prints and rebuilds the valuation math from today’s prices for both. If you own either name, are considering either name, or simply want to know where the most durable cash flows of the AI supercycle live while the market argues about everything else, this is the one to read.
Twice a week, I will release deep dives into stocks and sectors that fit into the 6 themes that I see winning in the coming years and decades: AI & Technology, Electrification & Energy, Reshoring & Sovereignty, Healthcare & Longevity, China & Asia, Resilience & Quality.
Take advantage of this once in a generation opportunity to build long term wealth by investing in great stocks that will deliver returns for your portfolio for years to come.
Ten days ago, in The Great AI Reckoning, I argued that the selloff tearing through the AI complex was a positioning event layered on top of real fundamental tensions, and that the answer was not to abandon the theme but to raise its quality and move up the visibility curve. I named the toll roads as the place to stand while the market works out whether the AI trade can pay for itself.

This week, the two widest of those toll roads reported:
ASML raised its 2026 revenue guidance by 15% at the midpoint, lifted its gross margin guide by three full points, confirmed that its 2027 EUV output is essentially sold out, and told the market it is evaluating a further 30% capacity step for 2028. The stock is down 4% since, at €1,535, roughly 12% below its high.
TSMC raised its full year growth guide from above 30% to above 40% in dollar terms, lifted its capex budget mid-year from $52-56bn to $60-64bn, something it almost never does, and committed another $100bn to Arizona. The stock is down 7% since, at NT$2,290.
This is the same mechanism I described a month ago in Nvidia/Broadcom: On Sale While the Crowd Chases the Periphery, one layer further down the value chain. Both companies beat, both raised, and the market, busy de-risking the most crowded factor in modern history, did not care. Those two names are flat since that piece while their forward multiples have compressed to 20.5x for Nvidia ($NVDA) and 24x for Broadcom ($AVGO). When guidance moves 15-20% higher and the price moves the other way, the forward multiple compresses through the denominator, and that compression is where the opportunity now sits.

The thesis of this piece in one sentence: ASML and TSMC are the two toll booths every dollar of AI capex must eventually pass through, both just printed quarters that extended visibility on that spend into 2028, and the momentum unwind has left them priced as if the traffic is about to stop.
The Reckoning asked whether the AI trade can pay for itself. This piece argues that while that question resolves, these two are where you wait, because their cash flows are the least speculative in the entire complex.
One sells the machines without which no advanced chip can exist.
The other manufactures every AI chip that matters.
Neither needs to know which lab wins, which model architecture prevails, or what a token costs in 2028. They need one thing to be true, that the world keeps needing more advanced semiconductors. That is not a projection resting on adoption curves and monetization models, which is very important to understand. This is physics, and it is order books.
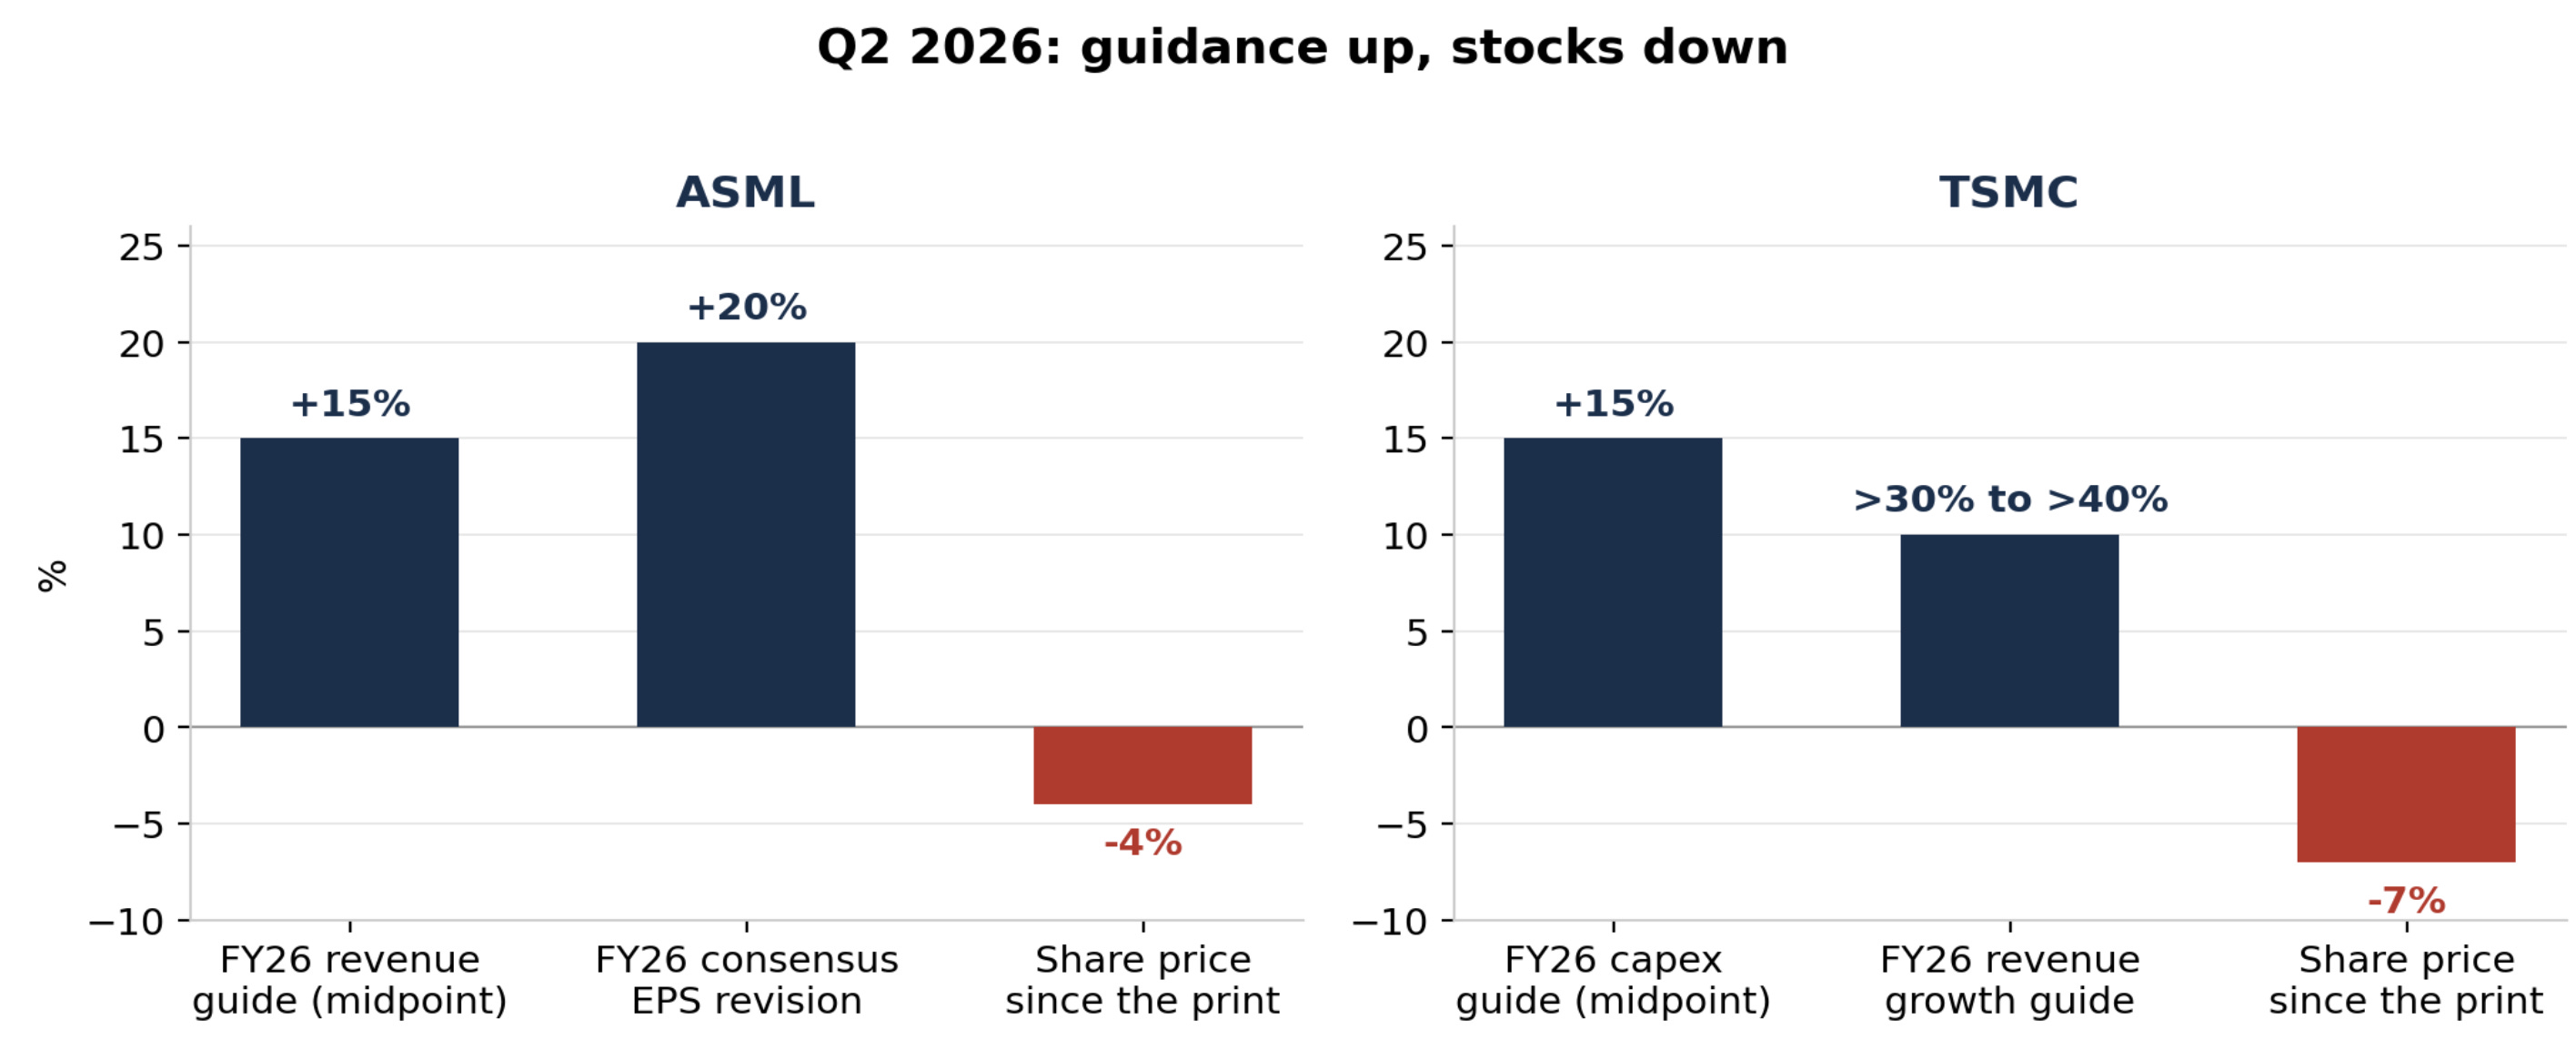
Guidance revisions from the Q2 2026 prints against the share price reaction. Both companies raised materially, both stocks fell.
Two toll booths, two different trades
Contrary to what many believe, these are emphatically not the same trade, which is why I think owning both is worthwhile.
ASML is the claim on the rate of change of capex, the more variance and the more expectations-driven of the two.
It sits at the top of the equipment layer with a 100% monopoly in EUV, an 80% plus share in DUV immersion, and no credible competitor or successor technology on any investable horizon.
Its earnings are geared to the rate of change of capex, which makes the stock more cyclical in the multiple even when the business is not, and its shares carry the residue of a specific disappointment.
Buy side expectations had run far ahead of any guidance the company could give. Whisper numbers for 2027 EUV capacity sat at 90 to 100 tools, ASML guided roughly 85, and a stock that had more than doubled in twelve months sold off on a print that raised full year earnings power by a fifth.
When a market punishes a company for promising only 30% more capacity per year, for two consecutive years, you are not trading fundamentals anymore. You are trading expectations that outran a supercycle.
TSMC is the claim on the existence of that capex, the more contracted and lower-variance of the two.
It manufactures effectively every advanced AI processor on earth (CPUs, GPUs, ASICs), its capex is pre-sold demand by construction, because its conservative culture only adds capacity against customer commitments, and its earnings for 2027 and 2028 are being physically poured in concrete today.
The variance of outcomes is narrower, the geopolitical discount is structural, and the multiple tells you exactly how much certainty you are being paid to accept.
The pairing is the widest moat in the equipment layer against the widest moat in manufacturing, the same toll road at two different toll rates.
